Moving a business asset to private use: settling up correctly
 Written by Ilias Aarrass6 min read · Published on · Last reviewed on
In short
Moving an asset into private use is a sale to yourself for tax: you settle at market value, usually remit 21 percent VAT on it and check the disinvestment addition.
- The difference between that value and the book value is a book profit or loss and flows straight into your profit.
- If you deducted no VAT at purchase, no VAT is due on withdrawal either.
- If you claimed the investment deduction, a disinvestment addition follows when your disposals that year together exceed € 2,900.
- There is no invoice and no bank statement: record the date, the value and the substantiation in writing yourself.
Business assets do not always leave through a sale. Sometimes you simply keep them: the old laptop becomes the home computer, the trailer is used privately only, the van stays parked when you stop trading. That is called a withdrawal, and for tax purposes it is not a non-event but a settlement moment. You take the asset out of your business at its current value, and the difference with the book value hits your profit. In some cases VAT is added, and sometimes an addition for investment deduction claimed earlier. This article walks through the three steps.
Step 1: determine the market value
You settle up at market value: what the asset would fetch today if sold to an arbitrary third party. Not the purchase price, and not the book value in your records either. For common items you substantiate that easily with a few listings of comparable examples; print or screenshot them and keep them with your records.
The difference between that value and the book value is a book profit or loss and flows straight into your profit. If you depreciated quickly, the book value is low and the book profit is higher than you expect. That is not a penalty: you are simply catching up on depreciation taken earlier.
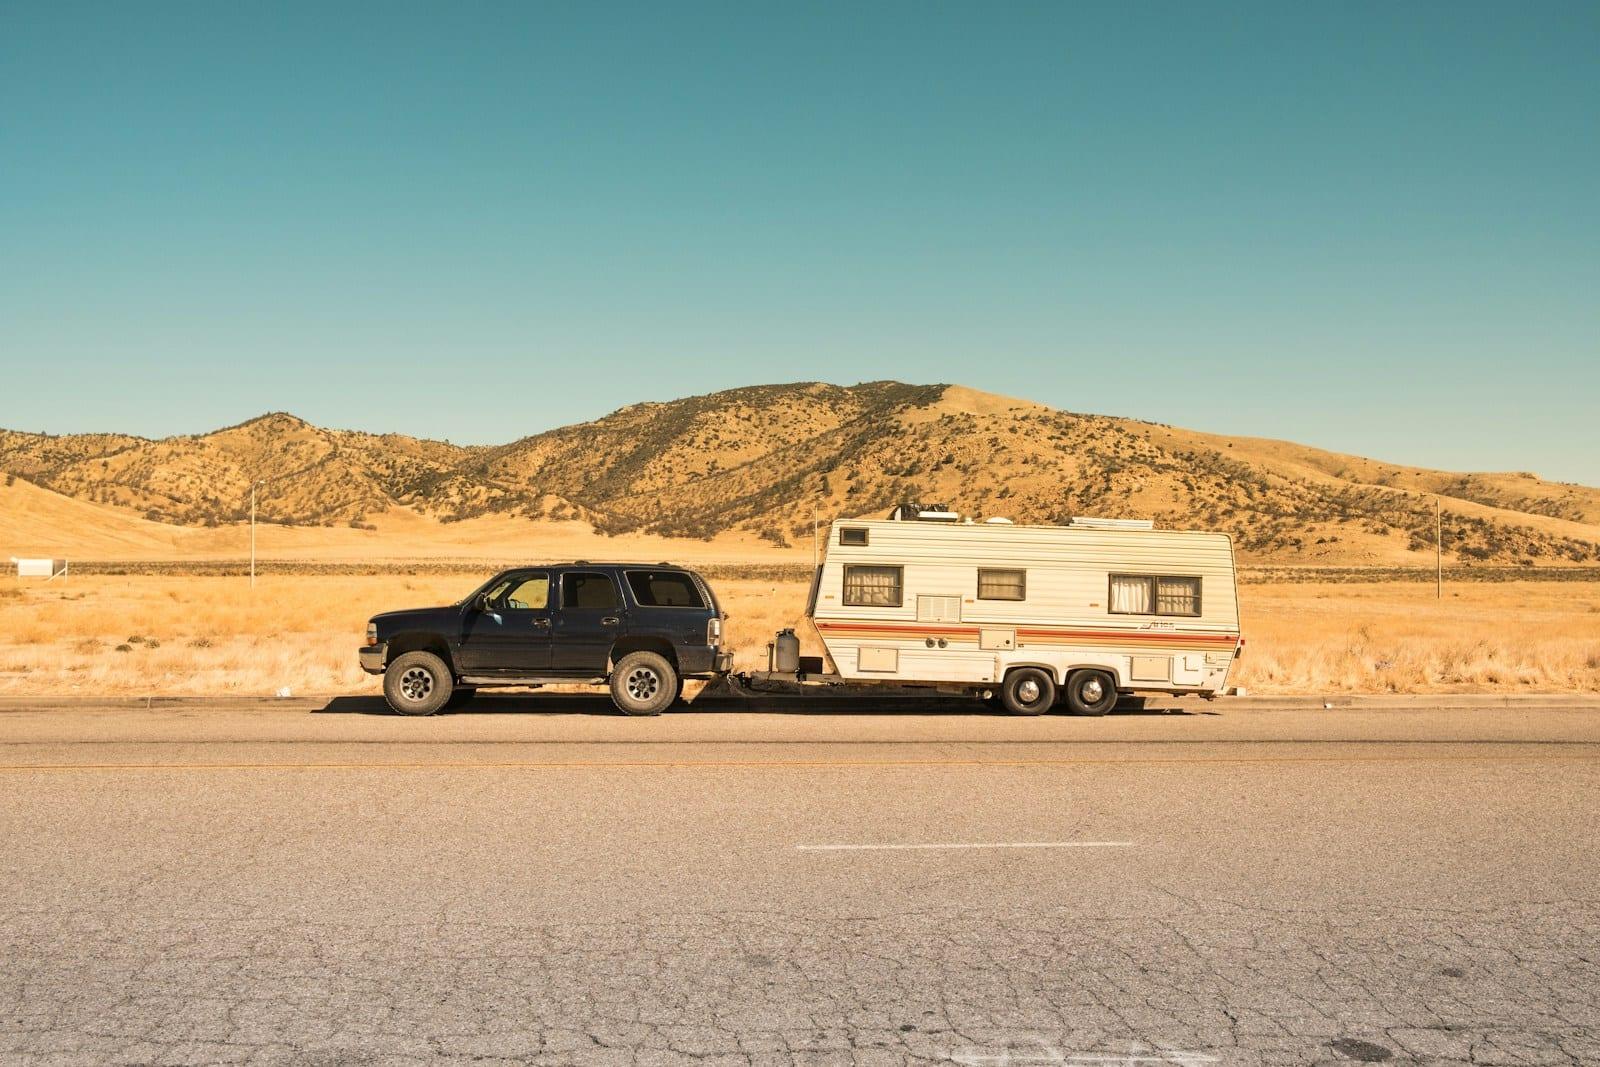
Worked example: a trailer taken into private use after three years
- Purchased in 2023
- € 4,000 excluding VAT
- Depreciated over three years
- € 2,400, book value € 1,600
- Current value per listings
- € 2,500
- Book profit
- € 900 added to profit
- VAT on the withdrawal
- 21% of € 2,500 = € 525
Result: You pay 525 euro of VAT in that quarter's return, and 900 euro of extra profit is taxed in your income tax. Expect roughly 300 euro of tax on that, depending on your rate.
Step 2: VAT on the withdrawal
If you deducted VAT at purchase, VAT law treats moving the asset to private use as a supply to yourself. You calculate 21 percent (or the rate applying to the goods) on the value at the moment of withdrawal, and report that as VAT due in that period's return. You do not issue an invoice for it, but you do record the calculation in writing.
If you did not deduct VAT at purchase, for example because you were under the small business scheme or bought the asset from a private individual, no VAT is due on withdrawal either. If you are still within the five or ten year adjustment term, also check VAT adjustment: the two rules can touch, and you never pay twice for the same thing.
Step 3: look back at the investment deduction
If you claimed the small-scale investment deduction on the asset and it leaves the business within five years of the start of the calendar year in which you invested, a disinvestment addition applies: part of that deduction is added back to your profit. That applies to a sale as well as a withdrawal to private use, so keeping the asset does not avoid it. The addition only bites if total disinvestments that year exceed € 2,900, the 2026 threshold.
Environmental or energy investments can also claw something back, see EIA and MIA. So always check which year you bought the asset and whether you claimed a deduction on it at the time before transferring it.
Recording it in your books
A withdrawal has no bank statement and no invoice, which makes it easy to forget. So record it as a document of its own in your books: which asset, which date, which value, which substantiation and which VAT. In your bookkeeping you write the asset off at the value determined, with a private withdrawal as the counter entry.
If you stop trading altogether, all remaining assets move to private use at once and you settle up on everything together. That is usually where the amount adds up, so run the numbers in advance. How that fits with the rest of your cessation settlement is covered in stopping or pausing, and where the line between business and private assets lies in business or private assets.
Frequently asked questions
Do I need to invoice myself?
No. A withdrawal is not a sale to a third party, so there is no invoicing obligation. You do record the calculation and the substantiation of the value in writing, so you can show it in an audit.
What if I keep using the asset partly for business?
Then it need not move to private use. If you use an asset more than ten percent for business, it may stay on the balance sheet and you only correct the private use. You withdraw it fully once business use has genuinely stopped.
Can I deduct a book loss?
Yes. If market value is below book value, the difference falls into your profit as a loss. Do make sure you have credible substantiation for that lower value.
Does this apply to my home workspace too?
A workspace in your own home follows separate rules, including whether the home is labelled as business or private property. See home workspace; different factors weigh there than with individual assets.
Sources
- Private withdrawals and market valueBelastingdienst · belastingdienst.nl
- VAT on business goods you start using privatelyBelastingdienst · belastingdienst.nl
- Disinvestment addition within five yearsBelastingdienst · belastingdienst.nl
Sources checked on
This article provides general information based on the rules known for 2026 and does not replace personal tax advice. For your specific situation, we're happy to take a look with you.